
Peyto: Get Paid While Waiting for the LNG Boom | 2026 Q3 Update
1 extracted signal · 0 resolved · 1 still active
 Peter Lukacs ResearchIndependent analyst profile
- Source published
- 12 Nov 2026, 14:13 UTC
- Recorded by Tahlil Plus
- 12 Nov 2026, 14:14 UTC
AI-generated source summary
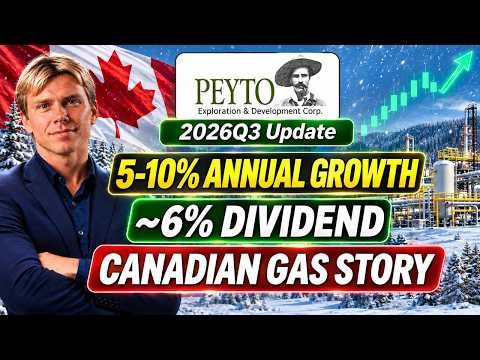
Peyto Exploration & Development Corp (PEY) is analyzed for its Q3 operational and financial performance, focusing on its natural gas production, hedging strategies, and LNG diversification. The company maintains solid production growth of 5-10% annually with capital expenditures around C$475-525M. While North American natural gas prices remain a near-term headwind due to supply outpacing demand, Peyto's robust hedging strategy and LNG-linked pricing agreements protect its cash flows. The balance sheet is healthy with a 32% debt-to-equity ratio and an 11x interest coverage ratio. Valuation scenarios for 2026-2030 outline a base case implied value of C$37.44 per share (off a current price of C$25.20), representing significant upside supported by strong dividend yields and free cash flow generation, despite ongoing share dilution from employee stock options.
AI-generated summary based on the source content.
Signal outcomes at a glance
Tracking LiveSignals in this source
Evidence and evaluation progress
- Original source published
The analyst published the original source item.
- Source recorded by Tahlil Plus
The public source was preserved as the evidence record for this case.
- Market predictions extracted
1 eligible signal linked to this case.
- Source processing completed
Source analysis and structured extraction completed.
- Outcome tracking started
Tahlil Plus began monitoring the extracted predictions.
- Live evaluation in progress
1 signal remains active.
Peter Lukacs Research
Platform-wide history, separate from this source evaluation.
Tahlil Plus independently records and evaluates public market predictions. Extraction may be AI-assisted and results follow the Tahlil Plus methodology. This information is not financial advice.