GPC (Best Value), AZO, ORLY, AAP, LKQ, AIT, GWW, FAST, MSM - Sector Analysis
4 extracted signals · 0 resolved · 4 still active
 Value Investing with Sven Carlin, Ph.D.Independent analyst profile
- Source published
- 15 Oct 2026, 12:00 UTC
- Recorded by Tahlil Plus
- 15 Oct 2026, 13:06 UTC
AI-generated source summary
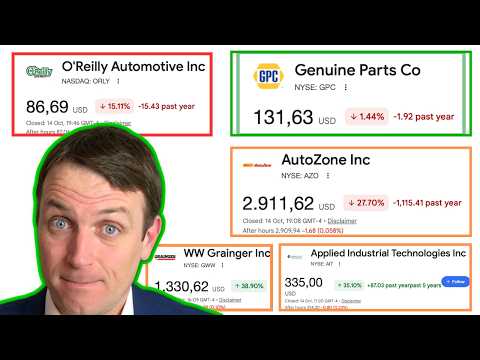
The analysis covers several companies in the automotive aftermarket sector, focusing on Genuine Parts Company (GPC), AutoZone (AZO), O'Reilly Automotive (ORLY), Advance Auto Parts (AAP), LKQ Corp (LKQ), Applied Industrial Technologies (AIT), W.W. Grainger (GWW), and Fastenal (FAST). The primary focus is on GPC, detailing its business separation, financial performance, and intrinsic valuation, with a conservative intrinsic value estimate around $105, suggesting a margin of safety at current prices. AutoZone (AZO) is highlighted as 'priced for near perfection' with a long-term uptrend, but a recent price decline offers potential value. O'Reilly (ORLY) also shows a strong uptrend, with a P/E ratio suggesting it might be fully valued. Advance Auto Parts (AAP) is presented as a turnaround play with significant recent stock price decline and challenges related to its business model and debt. LKQ Corp (LKQ) is identified as 'cheapest of the bunch' with potential, but also faces challenges. Applied Industrial Technologies (AIT) and W.W. Grainger (GWW) demonstrate strong historical growth and positive outlooks. Fastenal (FAST) shows good historical performance and growth, with strong ROIC. The analysis suggests that while industrials are expensive, automotive suppliers like GPC, AZO, and ORLY are priced for perfection, with GPC appearing relatively cheap after considering its business separation and potential revaluation. The valuation of GPC is estimated to be around $105 in a normal scenario, $150 in a best-case scenario, and $84 in a worst-case scenario, suggesting an upside. For AZO, a P/E ratio of 15 implies a market cap of $30 billion, half of its current valuation, indicating potential downside if free cash flow and net income are not realized. For AAP, the business model is questioned due to competition and buybacks, and the stock is considered significantly down from its peak. LKQ's turnaround potential is noted despite ERP issues. AIT and GWW are shown to have strong growth and valuations. Fastenal shows strong returns on invested capital.
AI-generated summary based on the source content.
Signal outcomes at a glance
Tracking LiveSignals in this source


Evidence and evaluation progress
- Original source published
The analyst published the original source item.
- Source recorded by Tahlil Plus
The public source was preserved as the evidence record for this case.
- Market predictions extracted
4 eligible signals linked to this case.
- Source processing completed
Source analysis and structured extraction completed.
- Outcome tracking started
Tahlil Plus began monitoring the extracted predictions.
- Live evaluation in progress
4 signals remain active.
Value Investing with Sven Carlin, Ph.D.
Platform-wide history, separate from this source evaluation.
Tahlil Plus independently records and evaluates public market predictions. Extraction may be AI-assisted and results follow the Tahlil Plus methodology. This information is not financial advice.