
ECO Dividend Yield 16.6%: How Okeanis Eco Tankers Became the Ultimate Tanker Income Play
1 extracted signal · 0 resolved · 1 still active
 Global News DailyIndependent analyst profile
- Source published
- 08 Oct 2026, 16:37 UTC
- Recorded by Tahlil Plus
- 08 Oct 2026, 18:48 UTC
AI-generated source summary
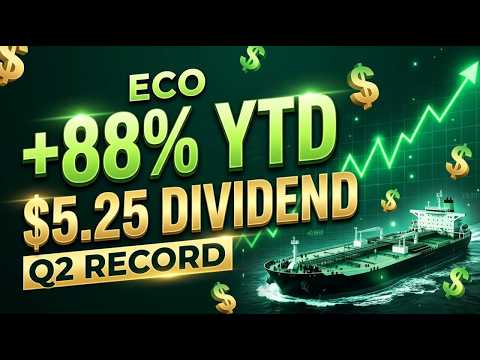
The tanker market is experiencing a boom driven by geopolitical disruptions, leading to record earnings. Shipping rates have surged from $2/bbl to $35/bbl, and daily earnings for VLCCs have reached $214,000/day, contributing to record Q2 2026 performance for ECO Tankers with $252 million in EBITDA and $231 million in net income. ECO Tankers is aggressively rewarding shareholders with a $5.25 quarterly dividend, representing 90% of its net income, while retaining only 10% for growth. Key advantages for ECO include a young fleet (average 5.6 years), scrubber-fitted vessels for lower fuel costs and regulatory compliance, and a low debt-to-value ratio under 25% with low-cost debt at 1.47%. The bull case is supported by persistent geopolitical risks extending trade routes, a replenishment cycle of global inventories requiring 1.8 million BPD to restock, trade shifts increasing US exports to Asia, and an aging global fleet with 28% of tankers aged 16-20 years. These factors are projected to sustain high ton-mile demand, potentially supporting a $100 price target for ECO, which is significantly above the analyst consensus of $67.85. However, the bear case highlights cyclical risks: order books have doubled to 28%, geopolitical normalization could collapse rates, the high dividend payout is unsustainable if rates drop 50%, significant insider selling ($9.3M over 3 months) occurred, and ECO has high spot market exposure with no safety net if rates plunge. The risk of oversupply from new vessel deliveries starting in 2028 could lead to a rate collapse by 2029. Despite the risks, the current market cap of $3.36B is less than double the replacement cost of $1.6B, suggesting potential value if current conditions persist, though the historical cyclicality of the industry presents a significant threat.
AI-generated summary based on the source content.
Signal outcomes at a glance
Tracking LiveSignals in this source

Evidence and evaluation progress
- Original source published
The analyst published the original source item.
- Source recorded by Tahlil Plus
The public source was preserved as the evidence record for this case.
- Market predictions extracted
1 eligible signal linked to this case.
- Source processing completed
Source analysis and structured extraction completed.
- Outcome tracking started
Tahlil Plus began monitoring the extracted predictions.
- Live evaluation in progress
1 signal remains active.
Global News Daily
Platform-wide history, separate from this source evaluation.
Tahlil Plus independently records and evaluates public market predictions. Extraction may be AI-assisted and results follow the Tahlil Plus methodology. This information is not financial advice.